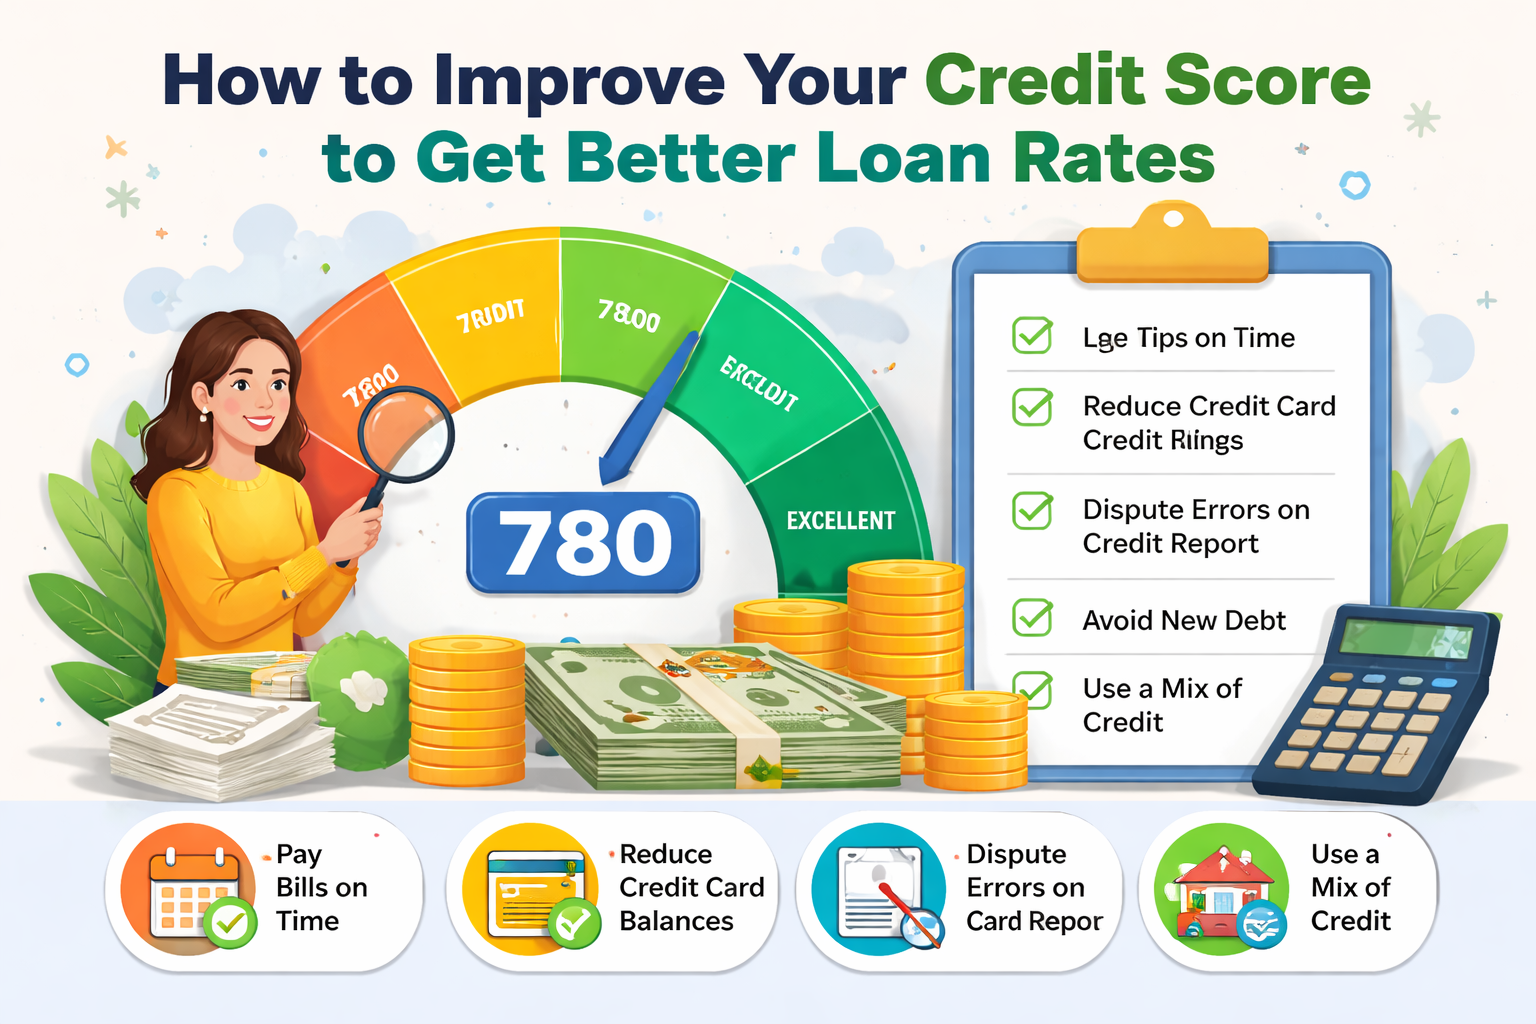
Your credit score plays a crucial role when applying for any type of loan. Whether you need a personal loan, payday loan, or emergency funding, lenders use your credit score to decide your loan approval and interest rate. A higher credit score helps you get better loan rates, lower EMIs, and faster approvals.
In this guide, we’ll explain how to improve your credit score with simple and effective steps.
Understanding Your Credit Score and Its Importance -
A credit score is a numerical representation of your financial reliability and creditworthiness. Lenders use it to check your repayment history and financial discipline.
Why credit score matters for loans:
* Lower interest rates
* Higher loan approval chances
* Flexible repayment options
* Higher loan amount eligibility
A good credit score means less risk for lenders, which leads to better loan offers.
Check Your Credit Report Regularly
Start boosting your credit score by carefully examining your credit report for errors and discrepancies.
Look for errors
* Check late payments
* Identify outstanding balances
Even a small mistake can reduce your credit score. Correcting errors can instantly improve your score.
Pay All EMIs and Bills on Time
Your track record of on-time payments significantly influences your credit rating.
Tips:
* Pay loan EMIs before the due date
* Never miss credit card payments
* Set auto-debit reminders
Even one missed payment can negatively impact your credit score for loan approval.
Reduce Credit Card Usage -
High credit utilization lowers your credit score.
Best practice: -
* Use less than 30% of your credit limit
* Avoid maxing out credit cards
* Pay outstanding balances regularly
Lower credit usage shows lenders you can manage money responsibly.
Avoid Applying for Multiple Loans Together -
Applying for many loans or credit cards in a short time leads to multiple hard inquiries, which reduces your credit score.
* Apply only when necessary
* Research loan eligibility before applying
* Choose the right loan once
Maintain a Healthy Credit Mix
A balanced mix of credit improves your score.
Examples:
* Personal loan
* Credit card
* Auto loan
Managing a variety of credit accounts effectively demonstrates your financial responsibility to lenders.
Keep Old Credit Accounts Active
Older accounts help improve your credit history length.
* Don’t close old credit cards
* Maintain small usage
* Pay bills on time
A long credit history helps you qualify for better loan interest rates.
Timeline for Boosting Your Credit Score
Enhancing your credit score requires patience and consistent financial discipline, with visible results over time:
* Minor improvement: 1–2 months
* Major improvement: 3–6 months
* Long-term strong score: 6–12 months
Consistency is the key.
Conclusion -
Improving your credit score is the smartest way to get better loan rates and easy approvals. By paying bills on time, reducing credit card usage, avoiding unnecessary loans, and maintaining a healthy credit profile, you can significantly boost your credit score.
A higher credit score not only saves you money on interest but also gives you financial confidence. Start improving your credit score today and unlock faster, cheaper, and stress-free loans with SpeedyCreditNet.